 ultimate-guide
How to Organize Personal Financial Documents in 2026
Table of Contents
- Step 1: Gather Every Financial Document You Own
- Step 2: How to Create a Home Filing System for Bills
- Step 3: How Long to Keep Tax Documents and Other Records
- Step 4: Best Digital Document Storage for Personal Finance
- Step 5: Automate Bill Payments and Track Recurring Costs
- Step 6: Financial Document Checklist for Estate Planning
- Step 7: Protect Your System with Disaster Recovery and Security
- Common Mistakes to Avoid When You Organize Financial Documents
- Frequently Asked Questions
Last Updated: October 1, 2026
Step 1: Gather Every Financial Document You Own
Learning how to organize personal financial documents starts with one uncomfortable truth: you cannot file what you have not found. This guide from LifeKeep walks through a complete system, from the first pile of paper to a disaster-proof archive your family can access. Most people underestimate how scattered their records are until they begin.
What Counts as a Financial Document
A financial document is any record that proves what you own, owe, earn, or have paid. That includes bank statements, credit card statements, tax returns, loan documentation, investment paperwork, insurance policies, property appraisals, and beneficiary information. Pay stubs, receipts for major purchases, and pension letters belong in the pile too.
Personal finance records also stretch beyond money: vaccination records, warranties, and vital records often live in the same drawer. Treat them as part of the same system.
The 30-Minute Quick Sort Method
Do not attempt to file anything during the first pass. Sort only.
- Clear a table and gather every paper pile in the house.
- Create four rough piles: tax, banking, insurance, and everything else.
- Put anything you cannot identify into a "decide later" box.
- Stop at 30 minutes, even if you are not finished.
The goal is momentum, not perfection. A common mistake is trying to build the perfect category list on day one, which stalls the whole project.
Step 2: How to Create a Home Filing System for Bills
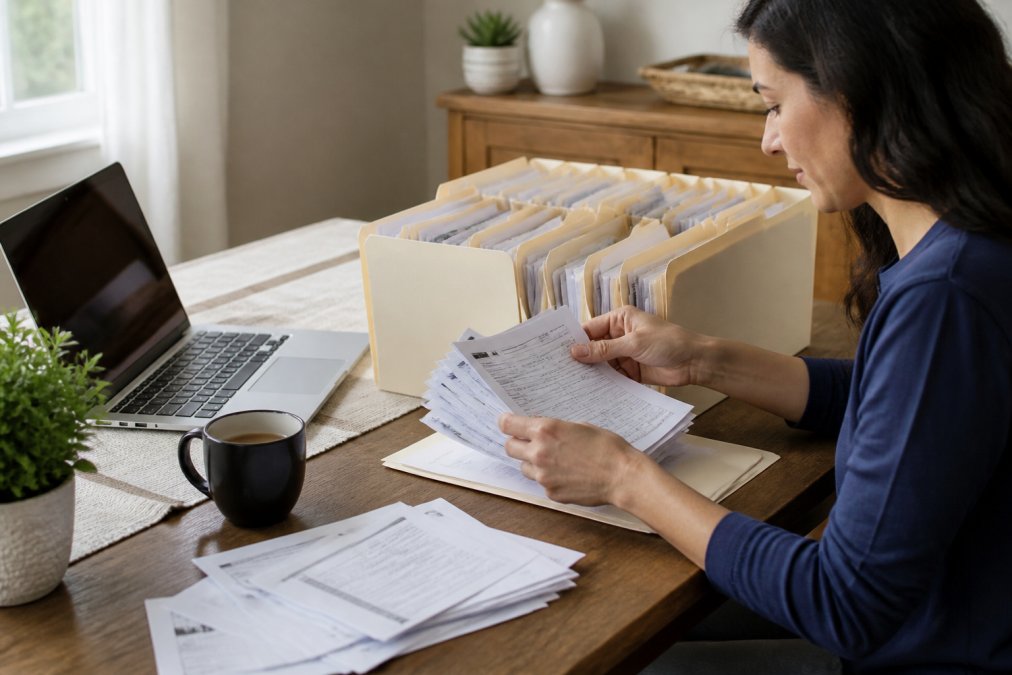
A home filing system for bills works when categories match how you actually think, not how an accountant would file them. Simplicity beats sophistication here: if a folder needs a sub-folder to make sense, the category is wrong.
Setting Up Categories That Actually Work
Start with five broad categories, then split only when a folder gets full:
- Tax: returns, supporting receipts, donation records
- Banking: statements, loan documentation, account reconciliation notes
- Insurance: policies, renewals, claim correspondence
- Property: deeds, appraisals, major repair receipts
- Personal: vital records, medical paperwork, warranties
Step 3: How Long to Keep Tax Documents and Other Records
Most tax records should be kept for three to seven years, depending on what they support, while documents like deeds and birth certificates stay permanently. Retention rules vary by country and situation, so check your tax authority's current guidance rather than relying on a rule of thumb.
Retention Schedule: What to Keep and What to Shred
| Document Type | Keep For | Why |
|---|---|---|
| Tax returns | 7 years | Supports income claims if audited |
| Bank and credit card statements | 1-3 years | Backs up deductions and disputes |
| Loan documentation | Until paid, plus 7 years | Proves settlement and interest |
| Insurance policies | Life of policy, plus 7 years | Needed for claims and renewals |
| Deeds and property appraisals | Permanently | Proves ownership |
| Vital records | Permanently | Cannot be replaced easily |
| Pay stubs | 1 year | Reconciles against tax returns |
Shred anything containing account numbers, your tax identifier, or signatures. Identity theft protection starts with what you throw away. For current retention requirements in your jurisdiction, check the official guidance from your national tax authority's record-keeping guidance.
Step 4: Best Digital Document Storage for Personal Finance
The best digital document storage for personal finance combines encrypted cloud backup with a clear folder structure you can search, not just browse. Digital-first filing is the single biggest upgrade most households can make: it removes the paper pile entirely and makes every record findable in seconds.
Building a Digital-First Workflow
Scan or download every statement as it arrives, then rename it with a consistent pattern: 2026-03 Bank Statement - Current Account.pdf. Consistency matters more than the tool you choose.
- Store originals in an encrypted cloud folder with two-factor authentication
- Keep a local backup on an external drive
- Use password management so credentials are never reused
- Sync only the folders you need on your phone
National Cyber Security Centre guidance on protecting personal data
Step 5: Automate Bill Payments and Track Recurring Costs
Automation is where financial document organization stops being a chore. Set every recurring bill to autopay, then review subscriptions quarterly so you are not paying for things you forgot you had.
Step 6: Financial Document Checklist for Estate Planning
A financial document checklist for estate planning answers one question: could someone else run your affairs tomorrow if they had to? Estate planning documents belong in an emergency binder that a trusted person can locate without guessing.
- Will and any trusts
- Beneficiary information for pensions and accounts
- Insurance policies with policy numbers
- List of bank accounts, loans, and investments
- Property deeds and vehicle titles
- Digital account inventory and password management instructions
- Contact details for your solicitor, accountant, and financial adviser
Making Documents Accessible for Family Members
Accessibility is the step most guides skip. Store the emergency binder in a secure location, tell one or two trusted people where it is, and keep a digital copy they can reach. Survivor planning fails when documents exist but nobody can find them.
Step 7: Protect Your System with Disaster Recovery and Security
Disaster recovery planning means your records survive fire, flood, theft, and hard-drive failure. The rule is simple: never keep your only copy in one place.
Common Mistakes to Avoid When You Organize Financial Documents
The biggest mistake is building a system too complex to maintain. Here are the failures that sink most attempts:
- Filing without a retention schedule, so nothing ever leaves
- Keeping everything digitally but never backing it up
- Storing all originals in one location with no copy elsewhere
- Forgetting to tell family members where the emergency binder lives
- Mixing personal and business records in the same folders
Frequently Asked Questions
What financial records should be kept for 7 years?
Keep tax returns and supporting documents for seven years, including W-2s, 1099s, receipts for deductions, and records of asset sales. The IRS generally has three years to audit a return but can go back six to seven years if it suspects underreported income. Bank statements, credit card statements, and pay stubs only need one year unless they support a tax return. Once you organize financial documents, label the seven-year file clearly so you know what stays and what can be shredded.
Should I keep financial documents in a physical file or digital cloud?
Most people benefit from a hybrid approach. Keep original signed documents like wills, property deeds, and insurance policies in a fireproof safe or safe deposit box. Scan everything else, including tax returns, bank statements, and investment paperwork, into a secure cloud folder. Digital filing saves space and makes documents accessible from anywhere. The best digital document storage for personal finance uses encryption and two-factor authentication, so check those features before uploading sensitive records.
How do I create a secure system for sensitive financial information?
Use a password manager to generate and store unique passwords for every financial account. Enable two-factor authentication wherever possible. For physical documents, store originals in a locked fireproof safe, and keep a backup set of scans in an encrypted cloud folder. Never email unencrypted tax returns or account numbers. Review who has access to your files at least once a year, and update beneficiary information on retirement accounts and insurance policies after any major life change.
What is the best way to organize my personal finances for my heirs?
Create a financial document checklist for estate planning that lists every account, policy, and obligation. Include bank accounts, retirement funds, life insurance policies, property deeds, loan documentation, and passwords for digital accounts. Store this list with your will and tell a trusted family member where to find it. A centralized system, whether a physical emergency binder or a shared digital vault, prevents your family from hunting through piles of paperwork during an already difficult time.
How often should I review and update my financial filing system?
Schedule a review every three months to file new statements, shred expired records, and reconcile accounts. Once a year, do a deeper audit: update beneficiary information, check that your retention schedule still matches your situation, and confirm that your emergency binder or digital vault is current. Busy professionals and parents often let paperwork pile up for months, so a recurring calendar reminder is the simplest way to stay on top of it.
What should I do with old financial documents I no longer need?
Shred anything containing account numbers, Social Security numbers, or signatures. A cross-cut shredder is safer than a strip-cut model. For bulk shredding, many office supply stores and community events offer secure shredding services. Before shredding tax returns, confirm you are past the seven-year retention window. If you have scanned the document and verified the digital copy is readable and backed up, the paper version can go. Never place unshredded financial documents in regular recycling.
Organizing personal financial documents is less about filing and more about building a system that survives a busy month. LifeKeep brings your bills, renewals, appointments, and reminders into one unified space, with a simple interface and centralized management of the tasks that slip through the cracks. Get started with LifeKeep and keep every deadline, renewal, and record within reach.